Income Protection Insurance
If you're unable to work because of illness or injury, under an employers group sickness scheme (Group IPI) salary is continued but is subject to tax and NI in the usual way.
The maximum amount of income you can replace through insurance is broadly the after-tax earnings you have lost, less an adjustment for state benefits you can claim. As with all insurance, it is important that you have the right type of policy which provides all that you need it to do for you.
Long-term income repayment policies usually come into play between the time when your employer stops paying sick pay, and when you collect your pension.
Shorter-term policies tend to be used to protect a mortgage, bank loan or other payment. These usually commence within a few weeks but stop entirely after 12 months or 24 months. Short-term policies often include unemployment and redundancy, unlike longer-term income protection cover which does not .
Income Protection Insurance only applies to products which pay you an income if you become unable to work due to sickness or injury. Policies to protect mortgages, loans or credit card debts are often called Accident Sickness Unemployment (ASU) policies.
We will happily explain this in more detail to you.
THE PLAN WILL HAVE NO CASH IN VALUE AT ANY TIME AND WILL CEASE AT THE END OF THE TERM. IF PREMIUMS ARE NOT MAINTAINED, THEN COVER WILL LAPSE.
MEET OUR Director/Wealth Manager
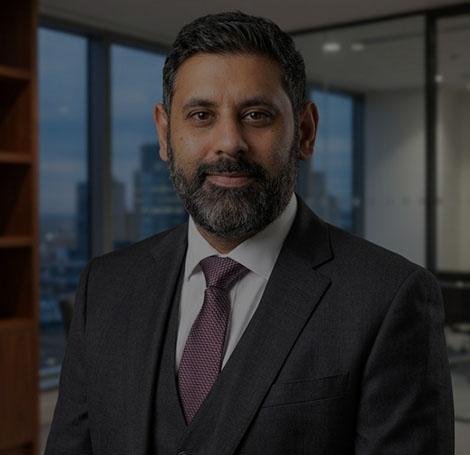
Aman Mashiana
Aman Mashiana is a strategic wealth management professional with more than 15 years’ experience building and leading advisory practices, managing substantial client portfolios, and delivering sustainable revenue growth in competitive financial markets.
The best solutions often start with the right questions!
FAQ'S
Not at all. We believe great financial planning should be accessible. Whether you are just starting to build your assets, navigating a major life transition, or managing multi-generational wealth, we tailor our advice completely to your current situation and future goals.
Our initial conversation is entirely exploratory and comes at no cost to you. It’s simply a chance to get to know each other. We’ll discuss your current financial picture, what you hope to achieve, and how we might be able to help. You won't need to sign anything or make any big decisions on day one.
We want to make managing your wealth as convenient as possible. We are happy to meet face-to-face at our office, or we can host a secure virtual meeting via video call (such as Microsoft Teams or Zoom) if that fits better into your busy schedule.
We believe in absolute fee transparency, meaning we agree on all costs upfront before any work begins. Depending on the complexity of your needs, our fees may be structured as a transparent percentage of the assets we manage, a flat fixed fee for a specific project, or an hourly rate. There are never any hidden costs or surprise bills.
Absolutely. It's incredibly common to lose track of old workplace pensions over time. We can help you trace your scattered accounts, review their current performance and fees, and—if it makes financial sense—consolidate them into a single, high-performing, and easy-to-manage retirement plan.
We don't believe in cookie-cutter portfolios. We take the time to deeply understand your time horizon, your specific life goals, and your personal comfort level with market volatility. From there, we build a diversified portfolio designed to grow your wealth steadily while keeping your risk well within your comfort zone.
Yes. Making money on investments is only half the battle; keeping it tax-efficient is just as important. We actively structure your wealth to minimize Income Tax, Capital Gains Tax, and Inheritance Tax, ensuring more of your hard-earned money stays with you and your loved ones.
Tax planning, estate planning & Inheritance Tax planning are not regulated by the Financial Conduct Authority.
Not at all. We believe great financial planning should be accessible. Whether you are just starting to build your assets, navigating a major life transition, or managing multi-generational wealth, we tailor our advice completely to your current situation and future goals.
Our initial conversation is entirely exploratory and comes at no cost to you. It’s simply a chance to get to know each other. We’ll discuss your current financial picture, what you hope to achieve, and how we might be able to help. You won't need to sign anything or make any big decisions on day one.
We want to make managing your wealth as convenient as possible. We are happy to meet face-to-face at our office, or we can host a secure virtual meeting via video call (such as Microsoft Teams or Zoom) if that fits better into your busy schedule.
We believe in absolute fee transparency, meaning we agree on all costs upfront before any work begins. Depending on the complexity of your needs, our fees may be structured as a transparent percentage of the assets we manage, a flat fixed fee for a specific project, or an hourly rate. There are never any hidden costs or surprise bills.
Absolutely. It's incredibly common to lose track of old workplace pensions over time. We can help you trace your scattered accounts, review their current performance and fees, and—if it makes financial sense—consolidate them into a single, high-performing, and easy-to-manage retirement plan.
We don't believe in cookie-cutter portfolios. We take the time to deeply understand your time horizon, your specific life goals, and your personal comfort level with market volatility. From there, we build a diversified portfolio designed to grow your wealth steadily while keeping your risk well within your comfort zone.
Yes. Making money on investments is only half the battle; keeping it tax-efficient is just as important. We actively structure your wealth to minimize Income Tax, Capital Gains Tax, and Inheritance Tax, ensuring more of your hard-earned money stays with you and your loved ones.
Tax planning, estate planning & Inheritance Tax planning are not regulated by the Financial Conduct Authority.