(Please note - Income Drawdown is a complex and constantly changing subject and the information provided here reflects the current situation. For more information call us today or complete our short enquiry form and we'll be pleased to help you further.)
Traditionally, when the time came to retire, most people with defined contribution (DC) pensions, either used their whole pension fund to buy an annuity or used the remainder to do so after taking their entitlement to tax-free cash (normally 25% of the fund). They did so because they either didn’t qualify for income drawdown or were not willing to accept (or were unable to afford) the associated investment risk.
Since income drawdown was introduced some years ago, anyone of retirement age with a DC pension has been able to take income directly from their pension fund without needing to buy an annuity. Now, with the introduction of new 'income drawdown' rules, anyone with a DC pension and age 55 (57 in April 2028) or over, can use income drawdown to provide the income they need in retirement. Pension savers who are currently in a capped drawdown can move out of that arrangement whenever they choose.
How Income Drawdown Works
Rather than exchanging your pension savings for an annuity (a fixed and regular income for life paid by the pension provider) the pension fund is left invested and you draw income directly from the fund. As the bulk of your pension remains invested the fund is still able to benefit from any growth (or not!) in the value of its investments. There’s no limit to the amount of income you can withdraw — you can draw as much (or as little) as you like, even the entire fund if you want.
And unlike an annuity, in a drawdown arrangement, the pension saver retains access to their pension pot.
Tax implications
Although you can withdraw up to 25% of your pension fund tax-free, anything else you withdraw from your pension pot will be treated as income and as such subject to the marginal rate of income tax.
Considerations
Income drawdown plans are a higher risk than a secured income arrangement such as a pension annuity, as the underlying assets of the fund are usually invested in the stock market. To ensure the pension fund does not run out of money, the member will require investment advice and regular reviews.
Some income drawdown products can be expensive in terms of charges, although they normally vary between 2% and 4% a year.
It’s also helpful if you have some experience in managing investments.
Please note we provide advice, not a facilitation process, if you engage us for services we will assess your suitability and we may deem that a drawdown is not suitable for your needs, in which case we will not recommend this.
THE VALUE OF PENSIONS AND THE INCOME THEY PRODUCE CAN FALL AS WELL AS RISE. YOU MAY GET BACK LESS THAN YOU INVESTED.
TAX TREATMENT VARIES ACCORDING TO INDIVIDUAL CIRCUMSTANCES AND IS SUBJECT TO CHANGE.
MEET OUR Director/Wealth Manager
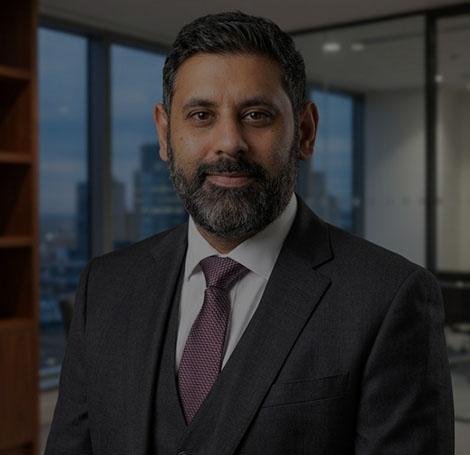
Aman Mashiana
Aman Mashiana is a strategic wealth management professional with more than 15 years’ experience building and leading advisory practices, managing substantial client portfolios, and delivering sustainable revenue growth in competitive financial markets.
The best solutions often start with the right questions!
FAQ'S
Not at all. We believe great financial planning should be accessible. Whether you are just starting to build your assets, navigating a major life transition, or managing multi-generational wealth, we tailor our advice completely to your current situation and future goals.
Our initial conversation is entirely exploratory and comes at no cost to you. It’s simply a chance to get to know each other. We’ll discuss your current financial picture, what you hope to achieve, and how we might be able to help. You won't need to sign anything or make any big decisions on day one.
We want to make managing your wealth as convenient as possible. We are happy to meet face-to-face at our office, or we can host a secure virtual meeting via video call (such as Microsoft Teams or Zoom) if that fits better into your busy schedule.
We believe in absolute fee transparency, meaning we agree on all costs upfront before any work begins. Depending on the complexity of your needs, our fees may be structured as a transparent percentage of the assets we manage, a flat fixed fee for a specific project, or an hourly rate. There are never any hidden costs or surprise bills.
Absolutely. It's incredibly common to lose track of old workplace pensions over time. We can help you trace your scattered accounts, review their current performance and fees, and—if it makes financial sense—consolidate them into a single, high-performing, and easy-to-manage retirement plan.
We don't believe in cookie-cutter portfolios. We take the time to deeply understand your time horizon, your specific life goals, and your personal comfort level with market volatility. From there, we build a diversified portfolio designed to grow your wealth steadily while keeping your risk well within your comfort zone.
Yes. Making money on investments is only half the battle; keeping it tax-efficient is just as important. We actively structure your wealth to minimize Income Tax, Capital Gains Tax, and Inheritance Tax, ensuring more of your hard-earned money stays with you and your loved ones.
Tax planning, estate planning & Inheritance Tax planning are not regulated by the Financial Conduct Authority.
Not at all. We believe great financial planning should be accessible. Whether you are just starting to build your assets, navigating a major life transition, or managing multi-generational wealth, we tailor our advice completely to your current situation and future goals.
Our initial conversation is entirely exploratory and comes at no cost to you. It’s simply a chance to get to know each other. We’ll discuss your current financial picture, what you hope to achieve, and how we might be able to help. You won't need to sign anything or make any big decisions on day one.
We want to make managing your wealth as convenient as possible. We are happy to meet face-to-face at our office, or we can host a secure virtual meeting via video call (such as Microsoft Teams or Zoom) if that fits better into your busy schedule.
We believe in absolute fee transparency, meaning we agree on all costs upfront before any work begins. Depending on the complexity of your needs, our fees may be structured as a transparent percentage of the assets we manage, a flat fixed fee for a specific project, or an hourly rate. There are never any hidden costs or surprise bills.
Absolutely. It's incredibly common to lose track of old workplace pensions over time. We can help you trace your scattered accounts, review their current performance and fees, and—if it makes financial sense—consolidate them into a single, high-performing, and easy-to-manage retirement plan.
We don't believe in cookie-cutter portfolios. We take the time to deeply understand your time horizon, your specific life goals, and your personal comfort level with market volatility. From there, we build a diversified portfolio designed to grow your wealth steadily while keeping your risk well within your comfort zone.
Yes. Making money on investments is only half the battle; keeping it tax-efficient is just as important. We actively structure your wealth to minimize Income Tax, Capital Gains Tax, and Inheritance Tax, ensuring more of your hard-earned money stays with you and your loved ones.
Tax planning, estate planning & Inheritance Tax planning are not regulated by the Financial Conduct Authority.